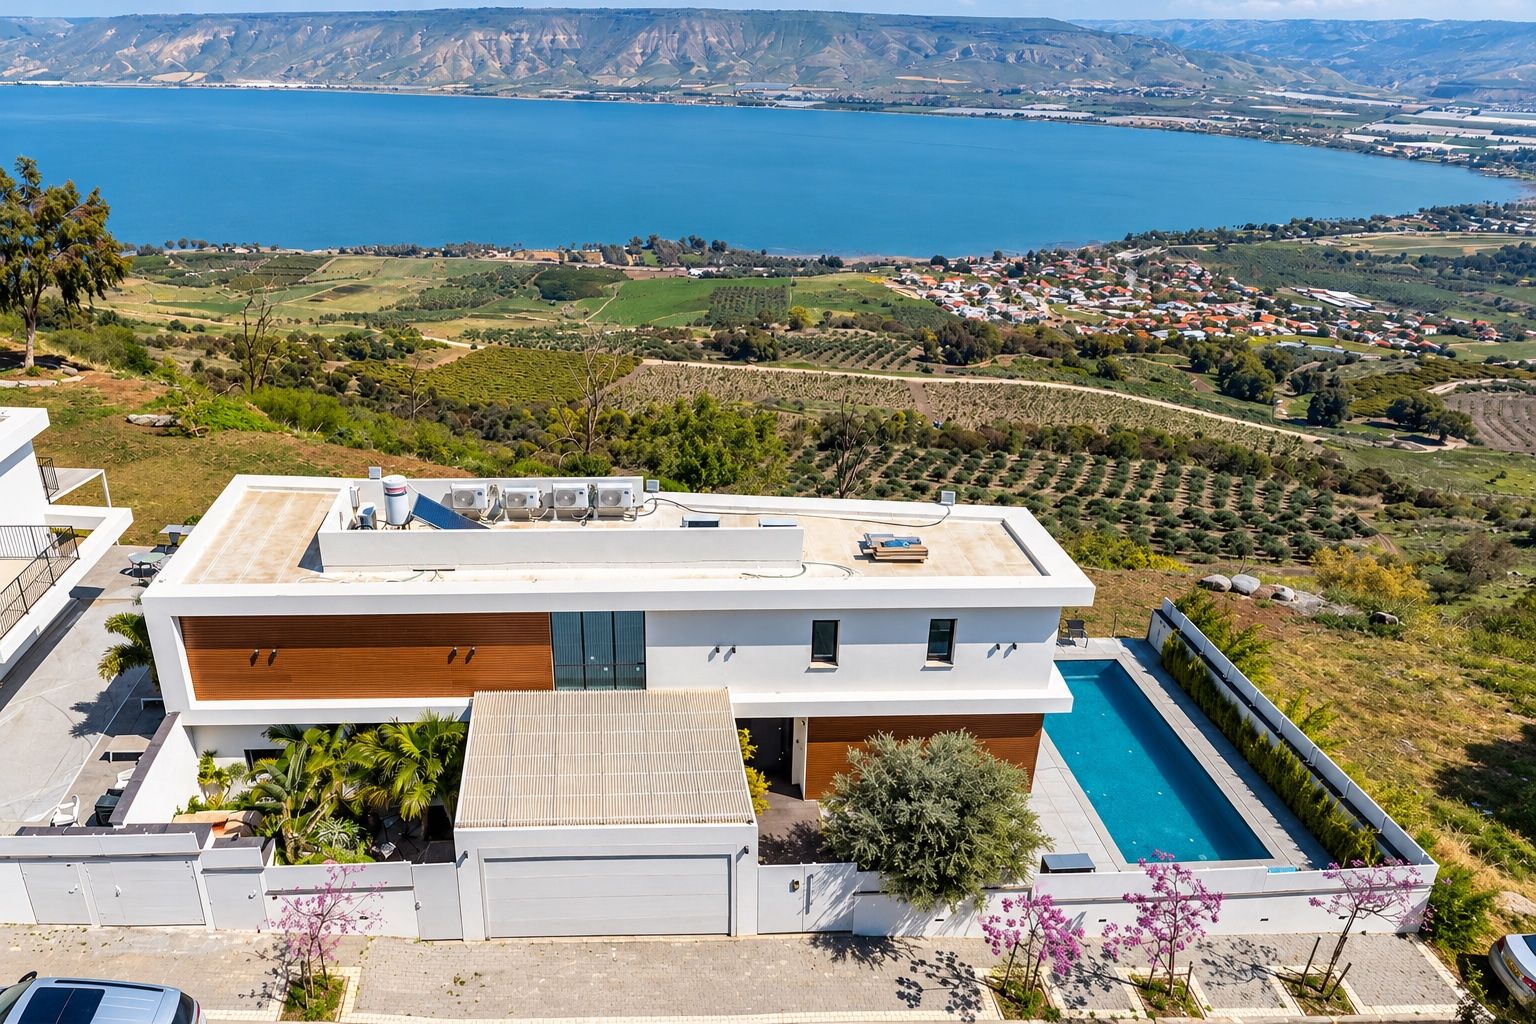
What you need to know when planning a property purchase in Israel while living in France, Belgium or Switzerland — and the questions to put to your advisers.
Buying in Israel while living in France, Belgium or Switzerland is entirely achievable, provided you understand that two systems apply at the same time: Israeli law and taxation for the purchase itself, and the rules of your country of residence for your personal obligations. This guide will help you prepare the right questions.
Are you able to buy? The first question to ask
In Israel, much of the land is owned by the State and managed by the Israel Land Authority: the buyer of a home on such land generally acquires a long-term leasehold, recorded in the Land Registry. The law regulates the transfer of certain land rights to people who are neither Israeli citizens nor residents, with specific treatment for those eligible under the Law of Return.
In practical terms: before making any offer, ask your lawyer to check the status of the land (land managed by the Israel Land Authority or privately owned) and what your personal circumstances allow.
The central role of the lawyer
Your Israeli lawyer checks the Land Registry extract (the “Tabu”) or the file held by the Israel Land Authority, confirms there is no mortgage or attachment, verifies that the buildings comply with permits, then negotiates the contract and oversees registration. Choose a lawyer who is independent of the seller, and ask for a written breakdown of their fees.
For the full process, see our guide The steps of buying property in Israel.
The overall budget: much more than the price
In addition to the price, allow for:
- purchase tax (mas rechisha), calculated according to your status (resident or not, new immigrant, other properties owned) — often the largest item;
- legal fees and, where applicable, agency fees;
- costs related to financing and currency exchange.
Financing the purchase
There are two main options:
- A mortgage in Israel: Israeli banks apply the Bank of Israel’s directives, which notably cap the proportion that can be financed depending on the type of property. For a non-resident buyer, terms are set case by case by the bank and are often more restrictive.
- Financing from France, for example secured against other assets, to be explored with your bank.
In either case, ask for a written quote before committing.
Currency exchange and transferring funds
The price is set in shekels (₪) and paid according to a payment schedule. Between signing and the final payment, movements in the euro/shekel exchange rate can significantly change your real cost. Plan ahead for how you will transfer the funds and discuss it with your bank.
Your obligations in France
If you remain a French tax resident, a few points should be reviewed with your adviser:
- Bank accounts abroad: an account opened in Israel must be declared every year with your income tax return (form 3916).
- Rental income: if you let the property, its taxation falls under the 1995 France–Israel tax treaty; in any event, it must be declared under French rules.
- Real estate wealth tax (IFI): depending on your assets, a property located abroad may form part of the wealth you have to declare.
Viewing: in person, and remotely on request
Nothing replaces an in-person viewing. Once your plans take shape, a short stay allows you to see the shortlisted properties; beforehand, a video call can be arranged on request.
Our role
We present properties that match your plans, organise viewings and facilitate communication with the professionals involved in your purchase. Legal, tax and financial checks are the responsibility of your lawyer, your tax adviser and your bank.
Official sources and references
- Israel Land Authority: land.gov.il
- Israel Tax Authority — purchase tax and forms: gov.il
- Bank of Israel — Directive 329 on housing loans (in Hebrew): boi.org.il
- Declaration of accounts held abroad (form 3916): impots.gouv.fr
- Tax treaty between France and Israel of 31 July 1995: “Conventions internationales” section on impots.gouv.fr